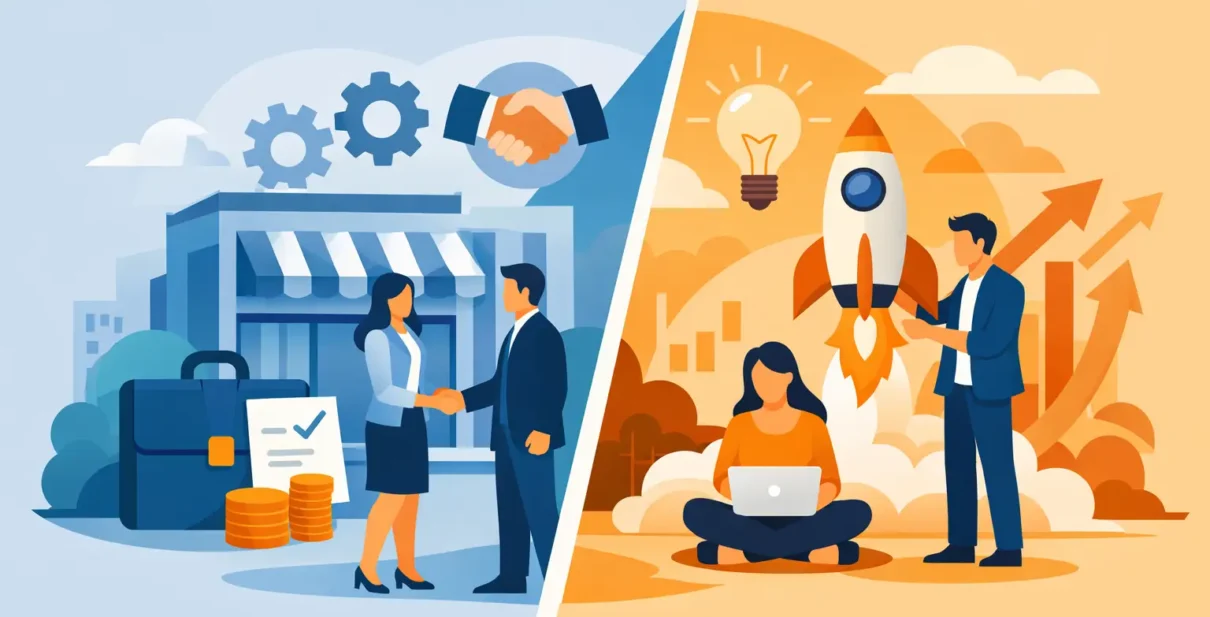
A profitable business with established customers can look like the faster route to market entry. A startup can look like the cleaner route to building exactly what you want. The buy existing business vs startup decision is rarely about ambition alone. It is a capital allocation decision that affects your cash flow, operating risk, immigration or expansion plans, and ability to scale across borders.
For entrepreneurs and investors entering the United States, Canada, or another new market, the right answer begins with a practical question: do you need to create a business model, or do you need to execute and improve one that already works?
Buy Existing Business vs Startup: The Core Difference
Buying an existing business means acquiring a functioning operation with some combination of customers, employees, equipment, supplier relationships, operating history, and brand recognition. You are paying for proof of demand, although the quality of that proof must be verified carefully.
Launching a startup means building those assets from the ground up. You have greater control over the concept, positioning, systems, and culture. In exchange, you accept uncertainty around product-market fit, customer acquisition, staffing, and the time required to reach consistent profitability.
Neither path is automatically safer. A weak acquisition can absorb capital just as quickly as an unproven startup. The key distinction is where the risk sits. With an acquisition, the risk is often hidden in past performance, valuation, liabilities, or transition. With a startup, the risk is visible but unresolved: the business has not yet demonstrated that customers will buy at a sustainable margin.
When Buying an Existing Business Creates an Advantage
An established business can provide immediate operational traction. If it has recurring revenue, experienced staff, documented processes, and durable customer demand, an owner can focus on improving performance rather than inventing the business from zero.
This is particularly valuable in regulated, relationship-driven, or locally competitive sectors. A service company with long-standing commercial accounts, a franchise location with consistent unit economics, or a specialized distribution business may have barriers to entry that a new operator would take years to overcome.
Existing businesses can also be easier to finance than startups because lenders and investors can assess historical financial statements, customer concentration, margins, and cash flow. Financing is never guaranteed, and the buyer’s experience, personal financial profile, and acquisition structure still matter. But a demonstrated track record generally offers a stronger lending narrative than a concept with projections alone.
For internationally minded entrepreneurs, acquiring an operating business may also support a more credible expansion plan. It can show active management, investment deployment, job creation potential, and a defined commercial presence. However, purchasing a business does not by itself create immigration eligibility. Visa and residency strategies require specialized legal guidance and must align with the investment, ownership, operational, and jurisdictional facts of the case.
The transition period is where value is protected
The business you buy may not be the business you operate six months later if the seller’s relationships, knowledge, or daily involvement are central to performance. A thoughtful acquisition structure should address the handover period, customer introductions, employee retention, training, and access to operating information.
A seller who is willing to remain involved for a defined transition can reduce disruption. At the same time, buyers should avoid relying entirely on verbal assurances. Key terms, non-compete obligations where enforceable, training commitments, and performance-based provisions should be documented by qualified professionals.
When a Startup Is the Better Strategic Choice
A startup is often the stronger option when the opportunity depends on a new market position, proprietary capability, or operating model that existing businesses have not adopted. If your advantage is a differentiated product, a technology-enabled service model, or a distinct customer segment, buying a traditional operation may constrain rather than accelerate growth.
Startups also give founders the freedom to establish systems correctly from the beginning. You can choose the technology stack, pricing strategy, vendors, brand identity, and governance model without inheriting outdated contracts or a culture resistant to change. This matters for businesses designed to operate in multiple markets, where standardized processes can make later expansion more efficient.
The trade-off is time. Most startups need a period of testing before revenue becomes predictable. Customer acquisition costs may exceed initial assumptions. Founders frequently underestimate the working capital required to cover payroll, marketing, inventory, compliance, and unexpected delays before the business reaches break-even.
A startup is not simply the lower-cost option because the purchase price is lower. Its real cost includes the capital required to survive the period before the business produces reliable cash flow. For a founder with deep industry knowledge, a proven sales channel, and patience to build, that investment may be justified. For an investor seeking immediate operating income, it may not be.
Compare the Capital You Need, Not Just the Purchase Price
A sound comparison looks beyond the price tag. Acquisitions typically require a larger upfront payment, plus legal, accounting, lender, and closing costs. Buyers also need post-closing liquidity for inventory, payroll, repairs, and growth initiatives. Spending all available capital on the down payment is a common and preventable mistake.
Startups may begin with lower initial investment, but they usually require staged funding. The founder must cover setup costs and absorb losses while building the customer base. In some sectors, the startup can become more capital-intensive than an acquisition before it reaches comparable revenue.
When reviewing either path, model a realistic downside case. Ask what happens if revenue falls 15 percent after an acquisition, or if a startup takes twice as long as expected to reach its first stable month of sales. Your plan should show how the business remains funded, not only how it succeeds under ideal assumptions.
Due Diligence Determines Whether an Acquisition Is Worth Buying
A business listing, broker summary, or seller-provided financial statement is a starting point, not proof. Acquisition due diligence should test the earnings that are actually transferable to a new owner.
Review at least the following areas before moving forward:
- Financial quality, including tax returns, bank records, normalization of owner expenses, debt, and working capital needs.
- Customer durability, including concentration, contract terms, churn patterns, online reviews, and the reason customers choose the company.
- Operational dependence, including whether key employees, suppliers, licenses, or relationships may leave with the seller.
- Legal and compliance exposure, including leases, permits, employment practices, tax obligations, insurance, and unresolved claims.
- Growth assumptions, including local demand, competitive pressure, pricing power, and the capital needed to achieve planned improvements.
For cross-border buyers, diligence should also examine ownership restrictions, tax residency considerations, currency exposure, reporting obligations, and the practical reality of managing the business from another country. The best transaction structure depends on the location, industry, buyer profile, and long-term expansion objective.
Franchises Offer a Third Route, With Their Own Trade-Offs
A franchise can sit between an independent acquisition and a startup. It offers an established brand, operating model, training, and support structure, while still requiring the franchisee to execute locally. Some franchise opportunities are new locations; others are resales of operating units.
The benefit is a tested framework. The limitation is reduced flexibility. Franchisees must operate within brand standards, pay ongoing fees, and understand territorial rights, renewal terms, transfer conditions, and local market saturation. A recognizable name does not remove the need for location analysis and financial review.
For entrepreneurs who want a repeatable business model and a potential path to multi-unit ownership, franchising may be compelling. For those whose advantage depends on innovation or complete independence, it may be too restrictive.
Make the Decision Based on Your Role After Day One
The most useful question is not whether acquisitions are better than startups. It is what kind of operator you intend to be after closing or launch.
Choose an existing business when you can evaluate its economics, have the capital to acquire and improve it, and are prepared to lead a transition. Choose a startup when you have a genuine market insight, the ability to sell before the model is fully proven, and enough runway to learn without forcing premature decisions.
For growth across borders, the decision also needs to fit the wider plan: market entry, ownership structure, financing, compliance, management presence, and future expansion. AN Global Group Holdings helps entrepreneurs assess these connected decisions through a cross-border lens, because the strongest opportunity is not merely the one you can buy or launch. It is the one you can operate well, protect financially, and grow with purpose.
Before committing capital, build a decision model that reflects your own experience, risk tolerance, time horizon, and target market. The right business path should give you more than ownership. It should give you a platform for durable growth.




1 Comment